> For the complete documentation index, see [llms.txt](https://docs.3jane.xyz/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://docs.3jane.xyz/levered-callable-capital-lcc/introduction.md).

# Introduction

What an LCC staker signs up for: promise yield on posted margin, in exchange for a binding obligation to fund USDC into USD3 when 3Jane calls.

Earn promise yield on your staked margin. In exchange, you promise to fund USDC into USD3 if 3Jane makes a capital call for deployment into fintech credit facilities.

In practice:

* **The margin is a bond, not the promise.** $75,000 of margin backs a $1,000,000 promise at launch terms. The promised USDC stays in your own custody until a call arrives.
* **The fee is paid on the promise.** Promise fees accrue on the full promised notional for as long as the promise stands, called or not, which is what levers the yield on the margin you posted.
* **A call is a deadline.** When 3Jane calls, you deliver your share in USDC within the funding window, 9 days at launch, and receive USD3 redeemable after a 35-day cooldown. From that point the funded capital carries USD3 credit exposure.
* **Missing a call costs margin.** Your margin is slashed into a Dutch auction, where a backstop bidder funds the shortfall in exchange for margin at a discount. That discount is the cost of the miss, and the surplus returns to you.

[Risks](/levered-callable-capital-lcc/risks.md) has the full list of what can go wrong.

Levered Callable Capital (LCC) is a market for balance-sheet capacity. A lending protocol's resource is capital. LCC's resource is promises, and that turns unfunded committed capital into a globally syndicated, permissionless primitive.

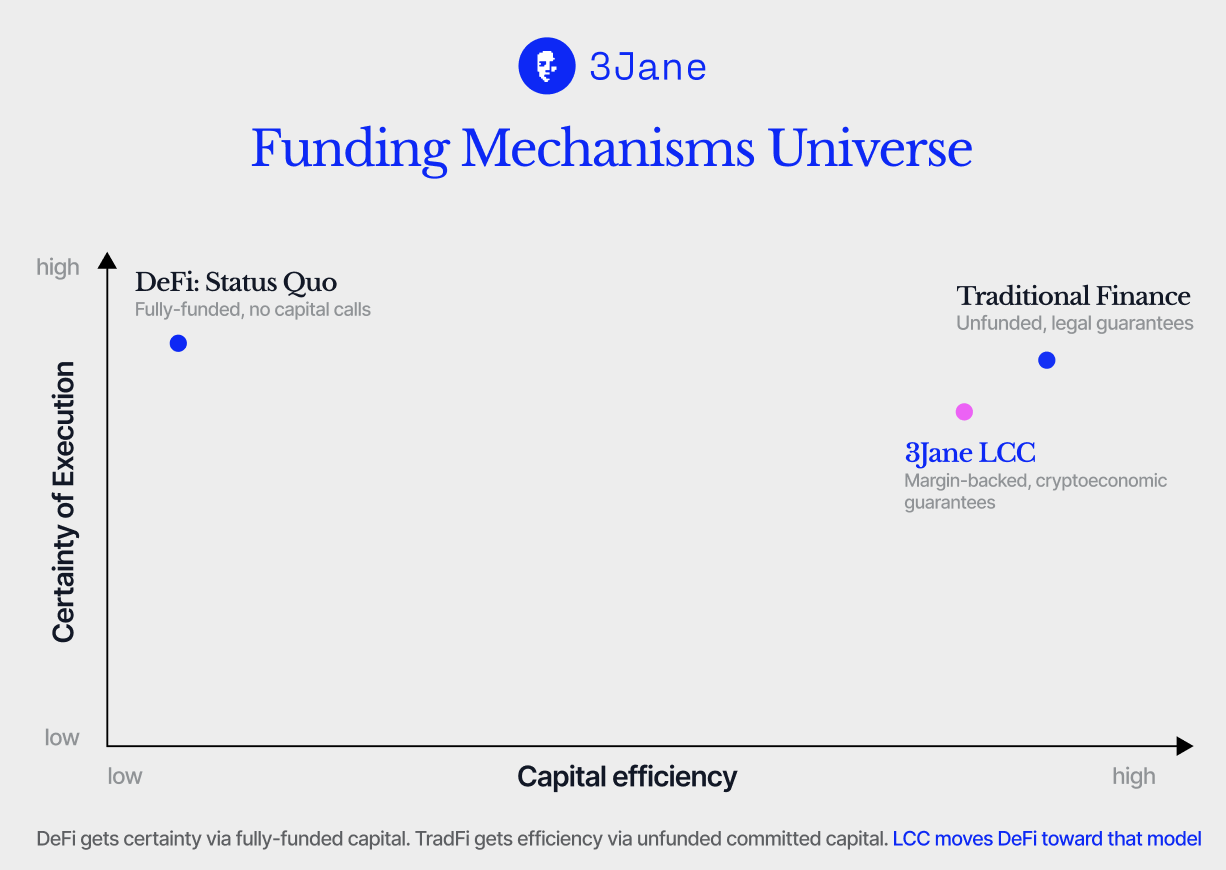
Enforcement is a margin-backed cryptoeconomic guarantee rather than a legal agreement, combining the capital efficiency and execution certainty of traditional finance with the scale, standardized clearing, and distribution advantages of DeFi. Committed capital becomes contingent capital: an internet-native asset class of balance sheet capacity that stays productive until needed and turns into real funding the moment credit demand appears.

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-cb0ababee4d915b15fabc5dd02280f11fd26323f%2Flcc-funding-mechanisms-universe.png?alt=media" alt="Funding mechanisms universe: DeFi status quo is fully funded with no capital calls, traditional finance is unfunded with legal guarantees, 3Jane LCC is margin-backed with cryptoeconomic guarantees"><figcaption><p>DeFi gets certainty via fully funded capital. TradFi gets efficiency via unfunded committed capital. LCC moves DeFi toward that model.</p></figcaption></figure>

Swapping legal enforcement for margin does more than port the capital call onchain; it changes what committed capital is.

### Capital efficiency with execution certainty

Uncalled capital never leaves the staker's wallet. It stays deployed wherever it already is, earning whatever it already earns, while the promise collects fees on top. 3Jane pulls USDC only when a deal is ready to fund, so neither side warehouses idle capital.

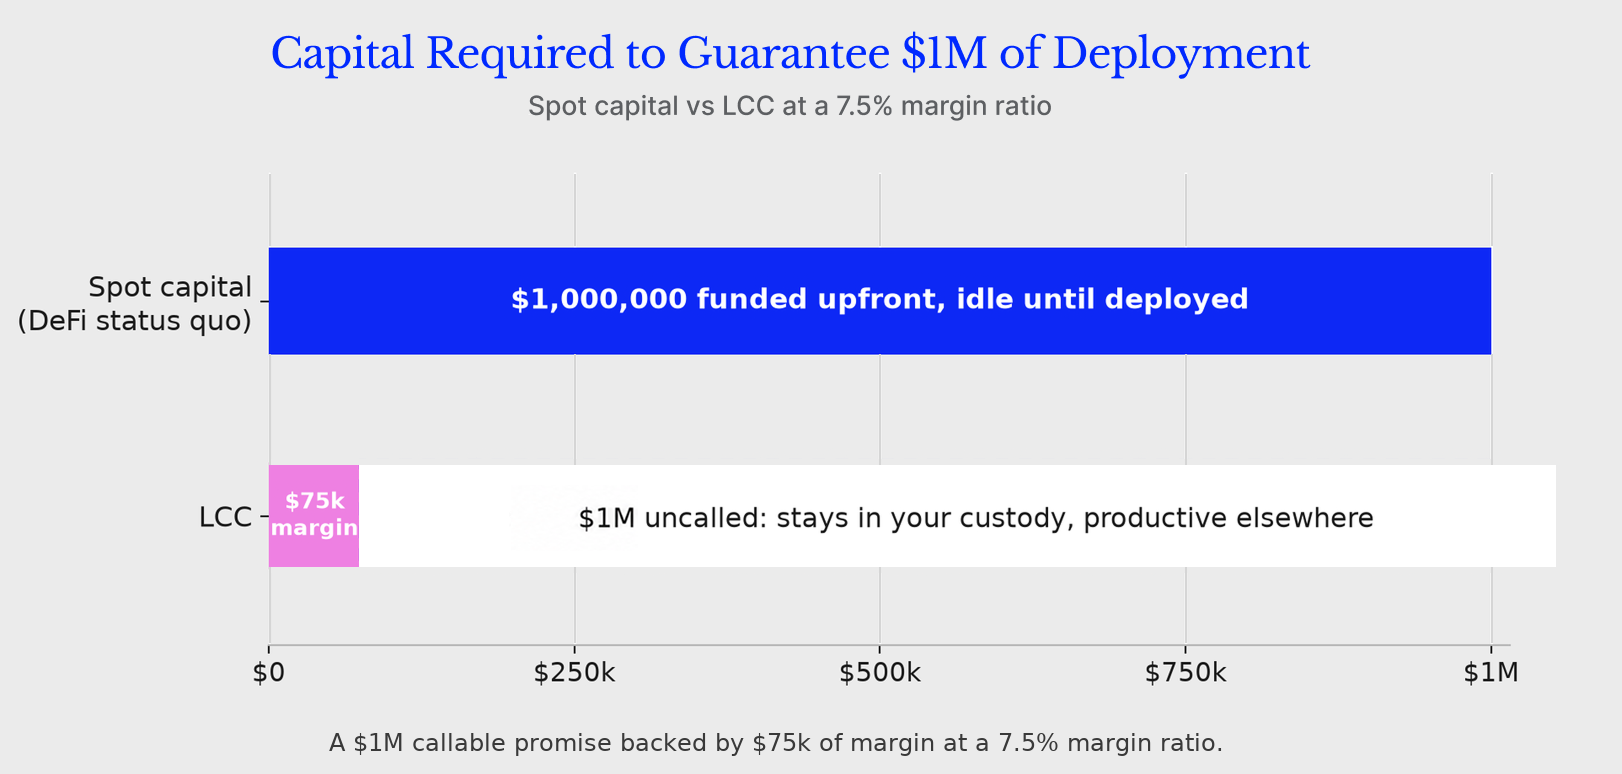
To guarantee $1M of deployment, the spot-capital model needs the full $1M deposited and idle. LCC takes a $75,000 performance bond and a callable claim on the rest. The trade is cheap for the issuer as well:

```
cost of prefunding = target yield - idle yield     (cash drag)
cost of promise    = promise fee
```

At an 8% USD3 target and a 3.5% idle rate, prefunding certainty costs about 4.5% a year against 1.25% for the promise, more than three times the price.

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-274021c4373dcf0dabf9e90588ff6dbe8c995ea6%2Flcc-capital-efficiency.png?alt=media" alt="Comparison: guaranteeing $1M of deployment requires $1,000,000 funded upfront under the spot-capital model, versus $75k of posted margin under LCC with the $1M promise uncalled and productive in the staker&#x27;s custody"><figcaption><p>The same $1M of funding certainty. Spot capital funds it upfront and lets it idle. LCC posts $75k of margin and leaves the $1M promise productive until called.</p></figcaption></figure>

### Contingent capital as a bearer asset

A TradFi commitment is a bilateral contract bound to one LP: it cannot trade or move, and the balance sheet that signed it is the only one that can ever honor it. An LCC promise is a bearer asset, defined by margin and terms rather than by who signed it, which lets contingent capital trade and transfer to whichever balance sheet prices it best and makes a secondary market for contingent capital a property of the asset itself.

### The auction as clearinghouse

A clearinghouse can only operate on standardized obligations, and every promise in a facility carries identical terms: every missed call is the same object, a shortfall backed by slashed margin, and the backstop auction can clear all of them. When an LP defaults in traditional finance, enforcement takes years of legal process. When a staker defaults in LCC, the auction reprices the missed call over a 4-day window and a bidder steps in to fund it.

### Permissionless capital formation

Because enforcement is margin rather than law, making a promise does not require negotiating fund documents or waiting on an allocation. Balance sheet capacity is syndicated globally through the protocol, and the pool of contingent capital scales with distribution rather than with a fundraising process.

***

See [Mechanism](/levered-callable-capital-lcc/mechanism.md) for how the guarantee works, step by step.