> For the complete documentation index, see [llms.txt](https://docs.3jane.xyz/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://docs.3jane.xyz/backing/fcc/credit-enhancement-and-loss-distribution.md).

# Credit Enhancement & Loss Distribution

{% hint style="info" %}
All numbers below are illustrative of the underlying structure and are not a reflection of the current USD3 backing.
{% endhint %}

This page maps the protection layers beneath each tranche and the loss distribution they sit on. Warehouse and forward-flow programs have had little prior history in DeFi, so their risks have rarely been mapped out in this context — this is that map.

## Layers of credit enhancement

Each tranche has its own stack of protection.

### USD3 credit enhancement

Cash flowing to USD3 sits behind a stack of protection that absorbs losses in order:

1. **Originator first-loss equity** — the originator's own capital beneath 3Jane (e.g. a 25% first-loss slice → 1.33x overcollateralization).
2. **Overcollateralization (OC)** — the eligible borrowing base exceeds the drawn balance; tested on a schedule (e.g. weekly).
3. **Reserves & performance triggers** — cash reserves and covenant triggers that trap cash or accelerate amortization if performance deteriorates.
4. **sUSD3 subordination** — the junior tranche absorbs losses before USD3 at the 3Jane capital-stack level.

### sUSD3 credit enhancement

sUSD3 absorbs losses ahead of USD3, but it is not first-dollar-loss capital. Its enhancement layer is **pool excess spread** — the net yield the pool generates, which absorbs losses before any principal is impaired.

* In a traditional deal the junior owes the senior a fixed coupon and eats any yield shortfall — it can lose money with zero defaults.
* 3Jane has no fixed coupon: both tranches earn a proportional share of pool yield (see [Pool Interest Rates](/usd3-susd3/pool-interest-rates.md)), so there is no shortfall to absorb.
* Losses net against pool yield before touching principal; sUSD3 principal is impaired only when realized losses exceed that yield.
* USD3 stands behind sUSD3, so this yield buffer is also the first layer in the overall loss order.

## Why granularity matters

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-9949aaf0915d05ed70b133d2a7c66e824dbf8fb0%2Ffcc-loss-distribution.png?alt=media" alt="Loss distribution: single-name vs granular pool"><figcaption></figcaption></figure>

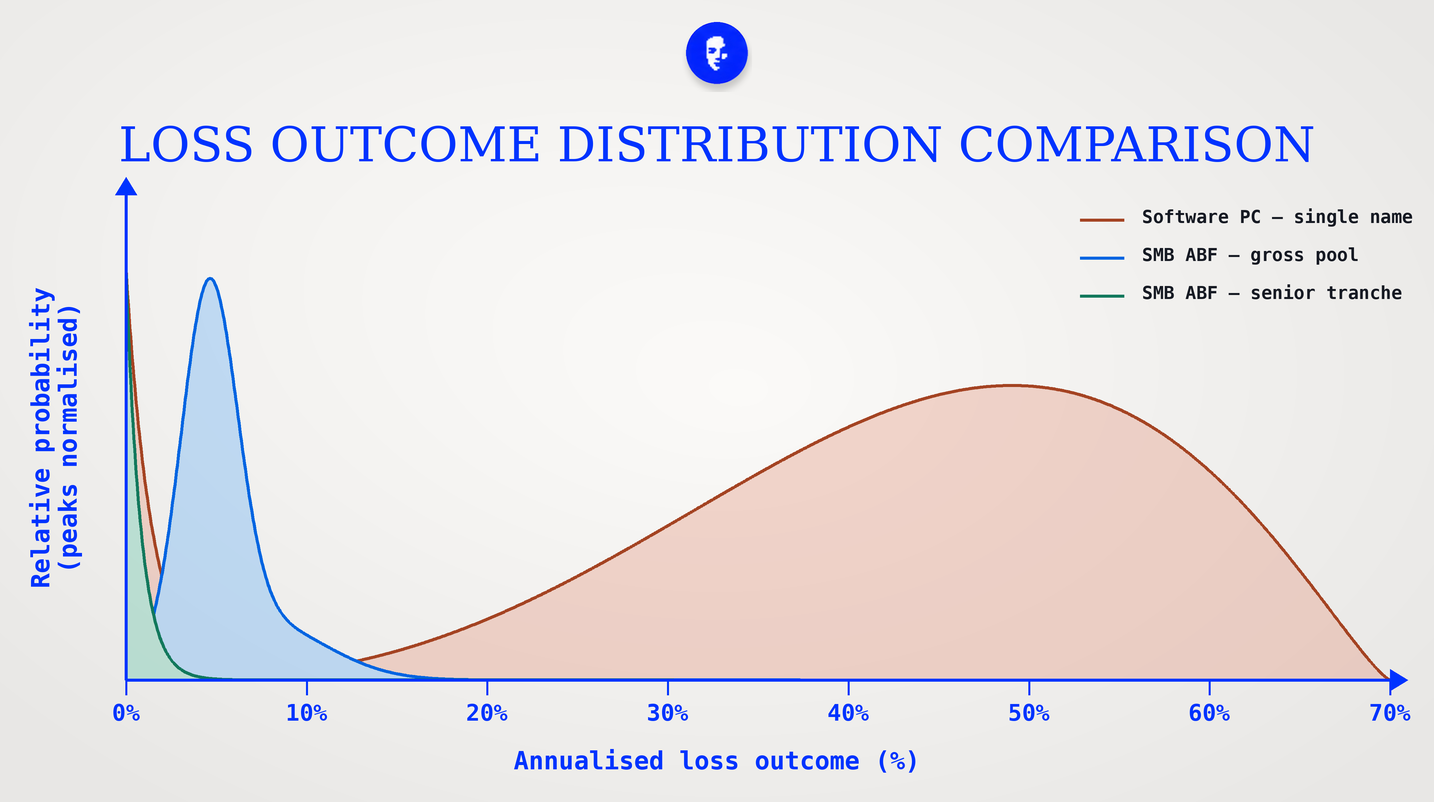
* Single-name corporate credit is **bimodal**: most loans pay at par, but a default jumps to restructuring-level loss severity.
* A granular SMB / consumer pool of \~3,000 obligors is **tight around expected loss**, because each obligor can fail independently.
* Expected loss can be similar across the two; the *shape* — and therefore the risk we are paid for — is completely different.

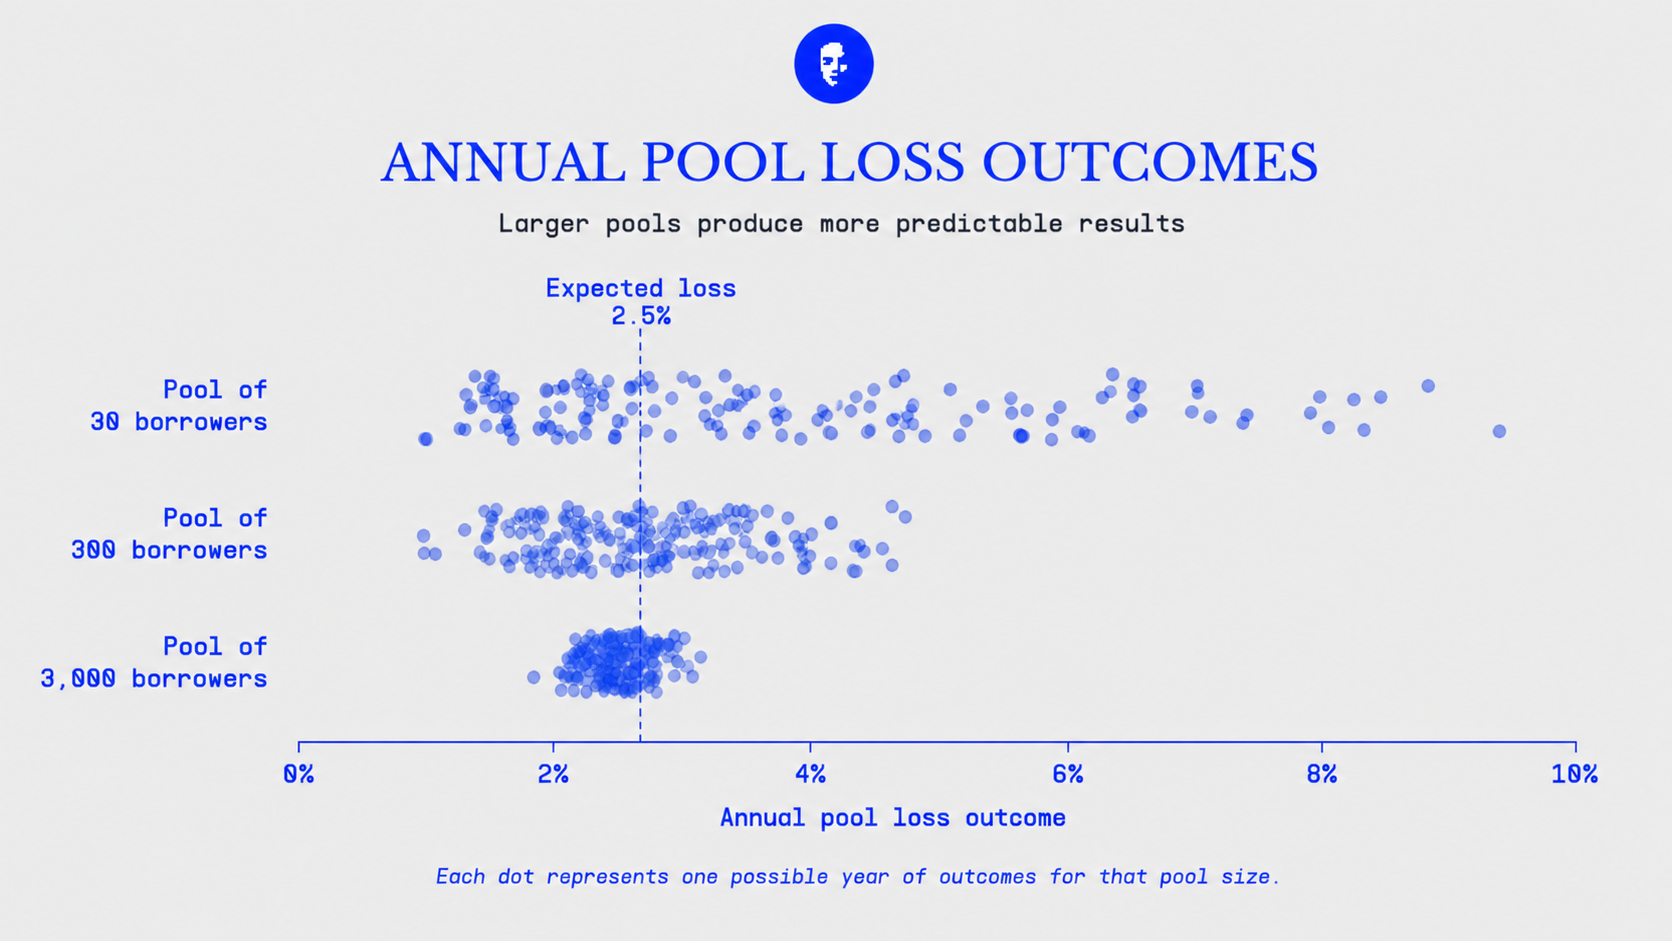
<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-f9e4d66e1c978a311c40e0a0cc733e778167449e%2Ffcc-diversification.png?alt=media" alt="N=30 vs N=3,000 loss distributions"><figcaption><p>Same expected loss, very different distributions. With 30 obligors, unexpected loss is wide and fat-tailed; with 3,000 obligors the distribution collapses to a tight spike and standard deviation falls by roughly two orders of magnitude.</p></figcaption></figure>

At a 5% annual default probability and 50% LGD, expected pool loss is 2.5%. But the standard deviation of pool loss falls from \~2 percentage points at N=30 to \~0.2 percentage points at N=3,000. Diversification compresses idiosyncratic risk first; correlation risk is then handled at the structuring level.

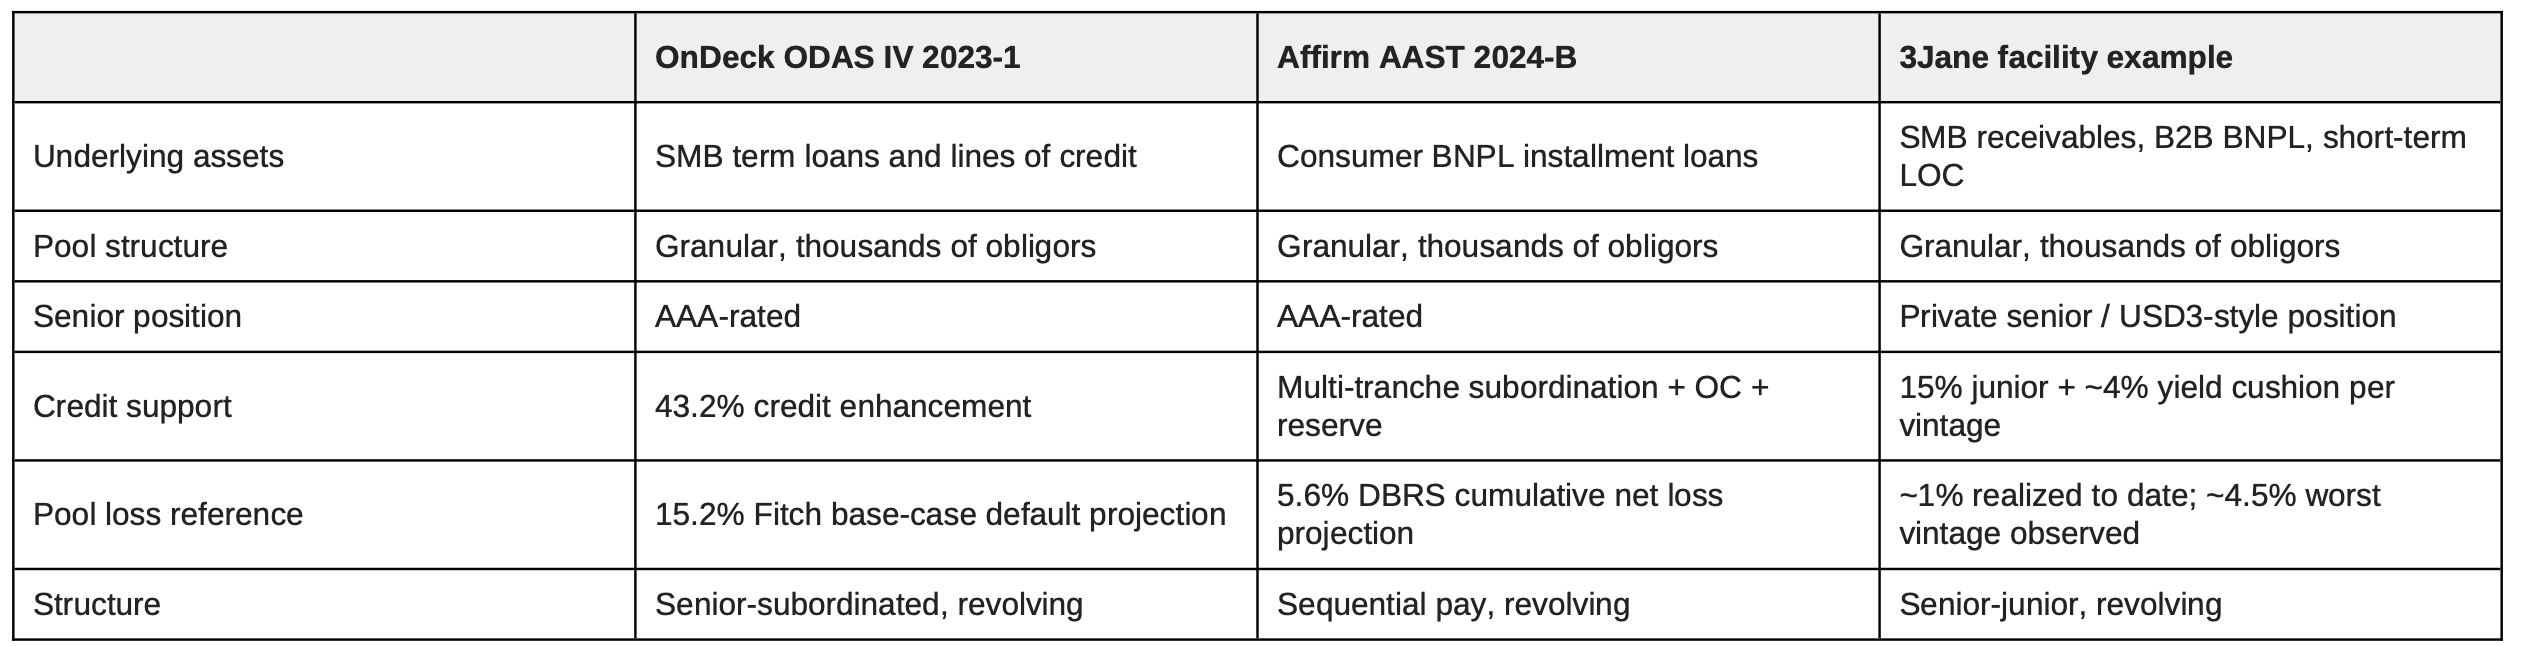
<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-0e8ea3b598fef26a35fd15f8411eb8b146ff9bbb%2Ffcc-abs-comps.png?alt=media" alt="OnDeck and Affirm ABS comparables"><figcaption><p>This is how the public ABS market routinely rates granular SMB and consumer receivables pools to investment grade. <em>Sources: OnDeck Asset Securitization Trust IV, Series 2023-1 (KBRA, July 2023); Affirm Asset Securitization Trust 2024-B (DBRS Morningstar, September 2024).</em></p></figcaption></figure>

## How structuring compresses the tail

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-2e9ca37a41a197f1ca69558bceb9decd61f26ecf%2Ffcc-per-vintage-capital-stack.png?alt=media" alt="Per-vintage capital stack"><figcaption><p>Capital stack on a per-vintage basis. Each cohort's net yield absorbs losses before any principal is impaired; the junior tranche absorbs anything beyond that; the senior takes losses only after both layers are exhausted. Markers show realised pool loss, the worst vintage in the book, and the senior break point.</p></figcaption></figure>

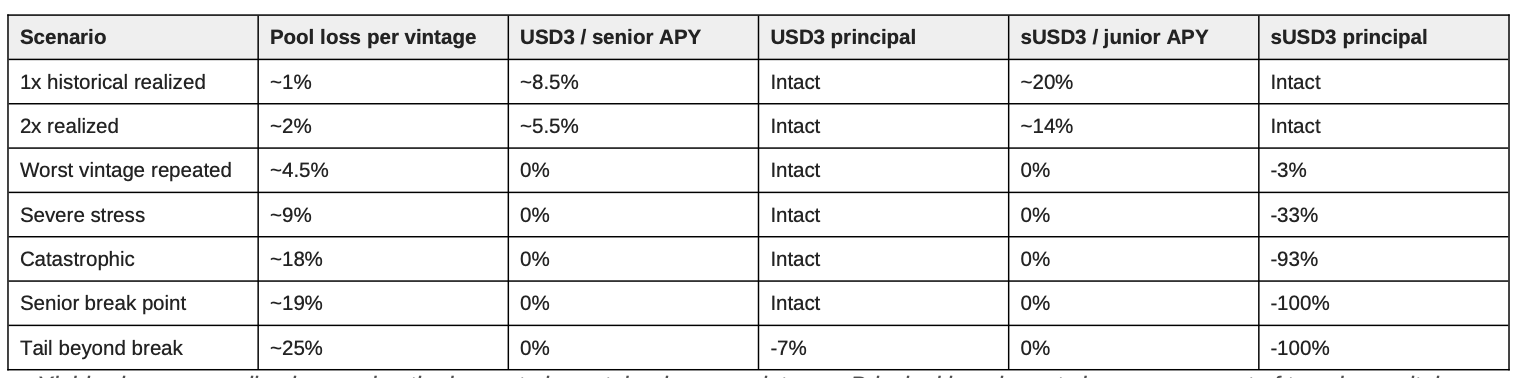
On the receivables book 3Jane underwrites, cumulative charge-offs sit around **1%** of disbursed principal. The worst single vintage came in around **4.5%**, and seasoned vintages collectively run under 2%. A facility example with \~4% of yield cushion and a 15% junior tranche puts USD3 / senior first-dollar principal loss at roughly **19% cumulative pool loss per vintage**.

## Correlation: borrowers failing together

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-10c3b2d6292d7ce9caa599dd3fbe380c5032fb2f%2Ffcc-correlation-copula.png?alt=media" alt="Correlation stress test"><figcaption></figcaption></figure>

To model correlation risk, the structure was pressure-tested with a single-factor t-copula (ν = 10, fatter-tailed than Basel's standard Gaussian framework) at three intra-pool correlation regimes: ρ = 5% (benign), ρ = 15% (Basel's SMB base case), and ρ = 30% (GFC-equivalent correlated stress).

The senior tranche holds up across the relevant range. The 99th-percentile pool loss — a once-a-century outcome — sits at **11.0%** (benign) and **14.5%** (moderate), well within the junior tranche. Even at GFC-equivalent correlation it reaches just **19.9%**, right at the senior break. The senior takes meaningful losses only in the 1-in-1,000 tail combined with GFC-equivalent correlated stress.

<figure><img src="https://1227041587-files.gitbook.io/~/files/v0/b/gitbook-x-prod.appspot.com/o/spaces%2Fv9UjcBMDpKGLDqrTs6IF%2Fuploads%2Fgit-blob-0e107162605231550a464366d899ad506f524c1e%2Ffcc-pool-loss-tranche-pnl.png?alt=media" alt="Pool loss to tranche P&#x26;L"><figcaption><p>Propagation from pool loss to tranche P&#x26;L, scenario by scenario. The senior is untouched until pool losses on a vintage cross ~19%; the junior is paid for absorbing everything in between.</p></figcaption></figure>

{% hint style="warning" %}
Target yields and loss figures are illustrative and based on the historically observed performance of the receivables book 3Jane underwrites. They are not guarantees — realised losses, correlation, and recoveries can differ. See [Risks](/risks.md) for protocol-wide risk factors.
{% endhint %}